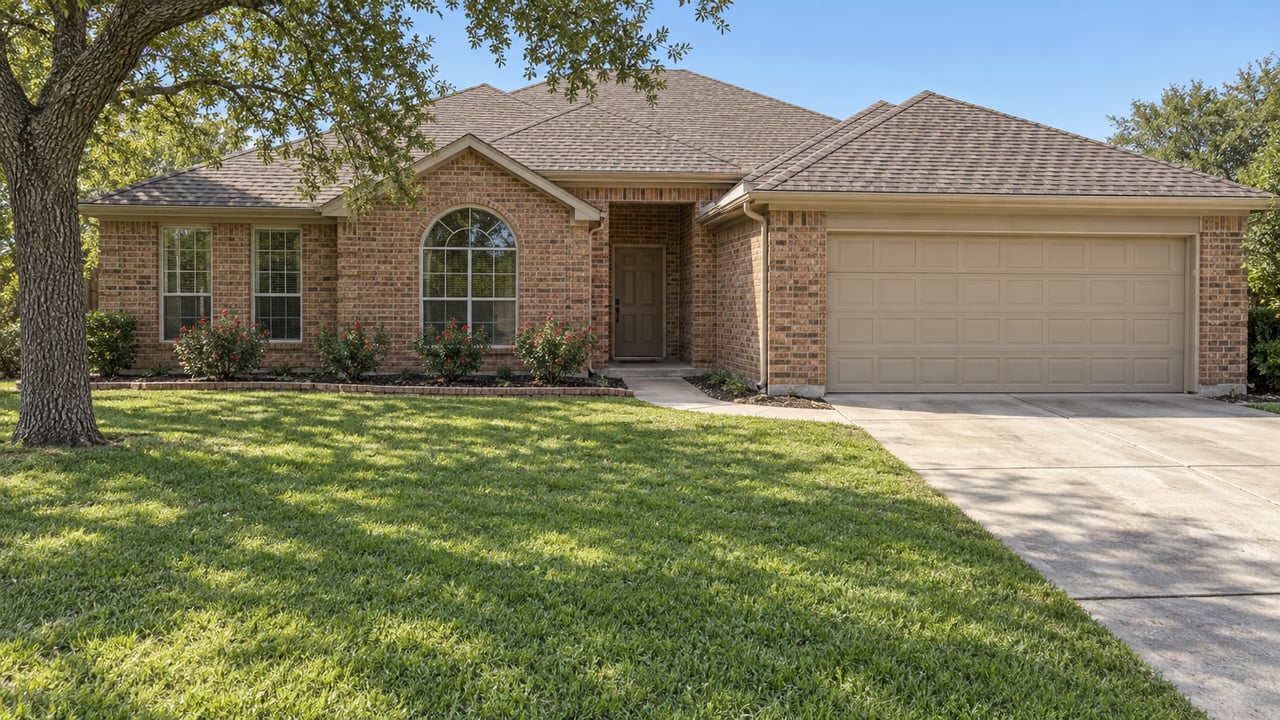
Tri Pointe Homes' October offer runs at View at the Reserve in Mansfield. Its fine print includes a sample comparison on a $530,000 home. At the promotional rate of 5.99% on a conventional 30-year fixed loan, with a 6.765% APR, the monthly principal and interest comes to $2,857. At what the builder calls the market rate of 7.5%, it comes to $3,335. That's a difference of $478 a month.
The same paragraph says how that rate gets paid for. Tri Pointe covers $19,225 in points and fees in the promotional example, compared with $7,432 in the market-rate example. To get the offer, a buyer has to buy an eligible home "for list price" and finance through Tri Pointe Connect, the builder's affiliated mortgage company. The contract has to be signed by October 31, 2026, and the loan has to close by December 18, 2026.
That condition matters most for anyone in Mansfield deciding between a new home and a resale home this fall. The builder's lower rate is paid for with the price negotiation a resale buyer usually gets to keep. To compare a new home and a resale home honestly, compare the whole deal on each side, not just the two rates.
What Mansfield Resale Buyers Were Getting in September
The resale side has its own discount, even if no one advertises it. The NTREIS MLS Summary Report from MetroTex, produced by the Texas Real Estate Research Center, shows Mansfield single-family homes at a 94.5% sold-to-list ratio for September 2026. On average, homes sold for about 5.5 percentage points below list.
Applied to Tri Pointe's $530,000 sample price, that gap would be $29,150. That's more than the $19,225 the builder spends on points and fees in its own example. The ratio is a citywide average, not a promise about any one house. Still, it shows what the list-price condition costs: the buyer gives up a gap that resale buyers in Mansfield were, on average, getting.
The rest of that September report adds context:
| Mansfield single-family, NTREIS | September 2025 | September 2026 |
|---|---|---|
| Closed sales | 97 | 66 |
| Median price | $465,000 | $490,000 |
| Average price | $468,264 | $528,665 |
| Median price per square foot | $183.43 | $182.33 |
| Sold-to-list ratio | 94.4% | 94.5% |
| Days on market | 70 | 65 |
| Active listings | 398 | 280 |
| Months of inventory | 4.0 | 3.3 |
The median rose $25,000 from a year earlier, but the median price per square foot fell slightly. So September buyers in Mansfield paid about what they paid a year ago per foot of house, and the higher median reflects larger homes in the mix. Price per square foot stayed flat and the gap below list stayed about the same, so resale buyers still had about the same room to negotiate as last fall.
The column that did change is active listings, down to 280 from 398. Each resale seller had less competition in September than a year earlier.
The report has one limit. NTREIS combines new and existing homes sold through the MLS and leaves out builder sales recorded outside the MLS. These figures describe the MLS side of Mansfield, which is mostly resale but not entirely.
Mansfield's October Builder Offers Are Built Differently
Builder incentives in Mansfield this fall differ in loan type, lender requirement and deadline. Here's what the builders selling in Mansfield communities published for October:
| Builder and community | Published offer | Lender condition | Deadline |
|---|---|---|---|
| Tri Pointe, View at the Reserve | 5.99% conventional 30-year fixed, 6.765% APR, plus up to $10,000 in closing credits, at list price | Tri Pointe Connect | Contract by 10/31/2026, close by 12/18/2026 |
| First Texas, Birdsong | 3.99% introductory rate on select inventory priced below $563,000 | CrossCountry Mortgage Branch 3861 | Close on or before 10/30/2026 |
| First Texas, Birdsong | Up to $20,000 Flex Cash, cannot be combined with other offers | CrossCountry Mortgage, Sawyer Team Branch 3861 | Contracts 9/1/2026 through 10/31/2026 |
| David Weekley, which builds at South Pointe | Up to $16,500 toward a rate lock, a rate buydown, or closing costs | Priority Home Mortgage | January 1 through December 31, 2026 |
| American Legend, M3 Ranch | Up to $20,000 toward closing costs | No lender named; loan application within five days of signing | Contract by 10/30/2026, close by 4/30/2027 |
| Coventry, South Pointe | Rates starting at 3.99%, 5.899% APR, on select quick move-in homes | "Terms and conditions apply" | No date shown |
The details are on each builder's own page: Tri Pointe's financing promotion, First Texas Homes at Birdsong, David Weekley's DFW event, American Legend at M3 Ranch, and Coventry at South Pointe.
Three offers in that table quote a rate, and Coventry's terms behind its rate aren't published. Three are cash toward costs or financing. The two lowest-looking rates, both 3.99%, don't share a published structure.
The 3.99% at Birdsong Is Fixed for Five Years
First Texas Homes says its Birdsong rate is an introductory rate on a 30-year FHA 5/1 adjustable-rate mortgage. The rate is "fixed for the first five years of a 30-year loan term." The disclosure continues:
"Beginning in year six, the interest rate adjusts annually based on the index, margin, and adjustment limits specified in the loan documents. The interest rate and monthly payment may increase after the initial five-year period."
The builder's financing example assumes a $450,000 price, 3.5% down and a minimum 680 credit score. It also notes that FHA mortgage insurance, taxes, homeowners insurance and HOA dues are added on top of principal and interest. The money comes from "a limited pool of committed funds," and the offer lasts until that pool runs out or the rate commitment expires.
Tri Pointe's 5.99% is published as a conventional 30-year fixed rate. One is a fixed rate for the life of the loan. The other is a five-year starting rate on a different loan program. The two numbers can't be compared directly.
The Lender Requirement Comes With Fine Print
Every builder above that names a lender says the same thing. You don't have to use their lender to buy the house, but you do have to use it to get the incentive. David Weekley's terms say, "You are NOT required to use Priority Home Mortgage as a condition for purchase of a home." Its financing credit still depends on using that lender.
The fine print adds other conditions:
- Unused credits are lost. First Texas says unused closing-cost credits are forfeited, have no cash value, and can't be applied to the down payment. Seller-paid credits are also subject to loan-program contribution limits.
- The lock and the build aren't tied together. Tri Pointe's terms are based on a 90-day rate lock and say that locking a rate "does not guarantee that your new home will be complete by the expiration of the interest rate lock period."
- Costs already paid stay paid. Tri Pointe says buyers will not get a refund of closing costs already incurred if the loan does not close or is not funded through Tri Pointe Connect "for any reason."
- Some timelines are short. American Legend's closing-cost offer requires a loan application within five days of signing and is subject to third-party contribution limits.
These conditions come from the builders' incentive terms, so a resale purchase financed with a lender of the buyer's choosing doesn't carry them. In a resale deal, the buyer's leverage is mostly in the price.
At South Pointe, Coventry Also Cut the Price
Builders don't hold firm on price everywhere. Coventry's South Pointe page lists a quick move-in Kilgore IV at 2906 Maretic Street in the South Pointe 50' section at $519,990, down from $576,450 and labeled "$56K off," with estimated completion in October 2026. The same page advertises rates starting at 3.99% with a 5.899% APR and sends buyers to its sales event for details.
Coventry's published event page applies the rate to "select quick move-in homes" and adds only "Terms and conditions apply. Contact us for details." Whether a price reduction like the one on Maretic Street can be combined with the rate is a question for Coventry's sales team. For comparison, Coventry's base prices at South Pointe start at $469,990 for 50-foot homesites, $525,990 for 65-foot and $591,990 for 75-foot.
On a quick move-in home with a posted price cut, a new-home purchase starts to look more like a resale negotiation.
October's Builder Offers Expire This Week
This week, most of the October terms above expire. American Legend's contract deadline and First Texas's Birdsong closing deadline are both October 30, 2026. Tri Pointe's contract window and First Texas's Flex Cash window close October 31. David Weekley's financing credit runs through December 31, 2026. Tri Pointe and First Texas both say their offers can change without notice, so the terms a buyer sees on a November tour may not match these.
The rate everything gets compared against hasn't moved much. Freddie Mac's Primary Mortgage Market Survey put the national average 30-year fixed rate at 7.40% as of October 15, 2026, unchanged from the week before and up from 6.27% a year earlier. That's a national weekly average. Tri Pointe's 7.5% "market rate" is the builder's own figure for its own example, so the two shouldn't be treated as the same number.
This post is general information, not financial or legal advice. Loan terms depend on each borrower, so please review any offer with your own lender and the right professionals before you sign.
If you're weighing a builder's rate offer against a Mansfield resale home, or you're a seller pricing against the new-home incentives down the road, the Angelique Burkett Team can put both sides on one page in real dollars. Start with a Free Home Valuation and we'll show you where your home sits against this fall's offers.